Policy and settlement information
Kansas home and renters guidance explains reporting, adjuster assessment and questions about coverage or settlement.
Understand the separate insurance and roofing decisions after damage to a Kansas home.
The roof inspection identifies physical condition and useful construction options. The insurer decides coverage under the policy, including the cause of loss, exclusions, limits and deductible. Those decisions relate to one another without being the same decision.
Report damage promptly to the insurer and follow the policy requirements. Keep available records of the event, damage and temporary work. Stay off the roof; a claim does not require you to inspect an unsafe area.
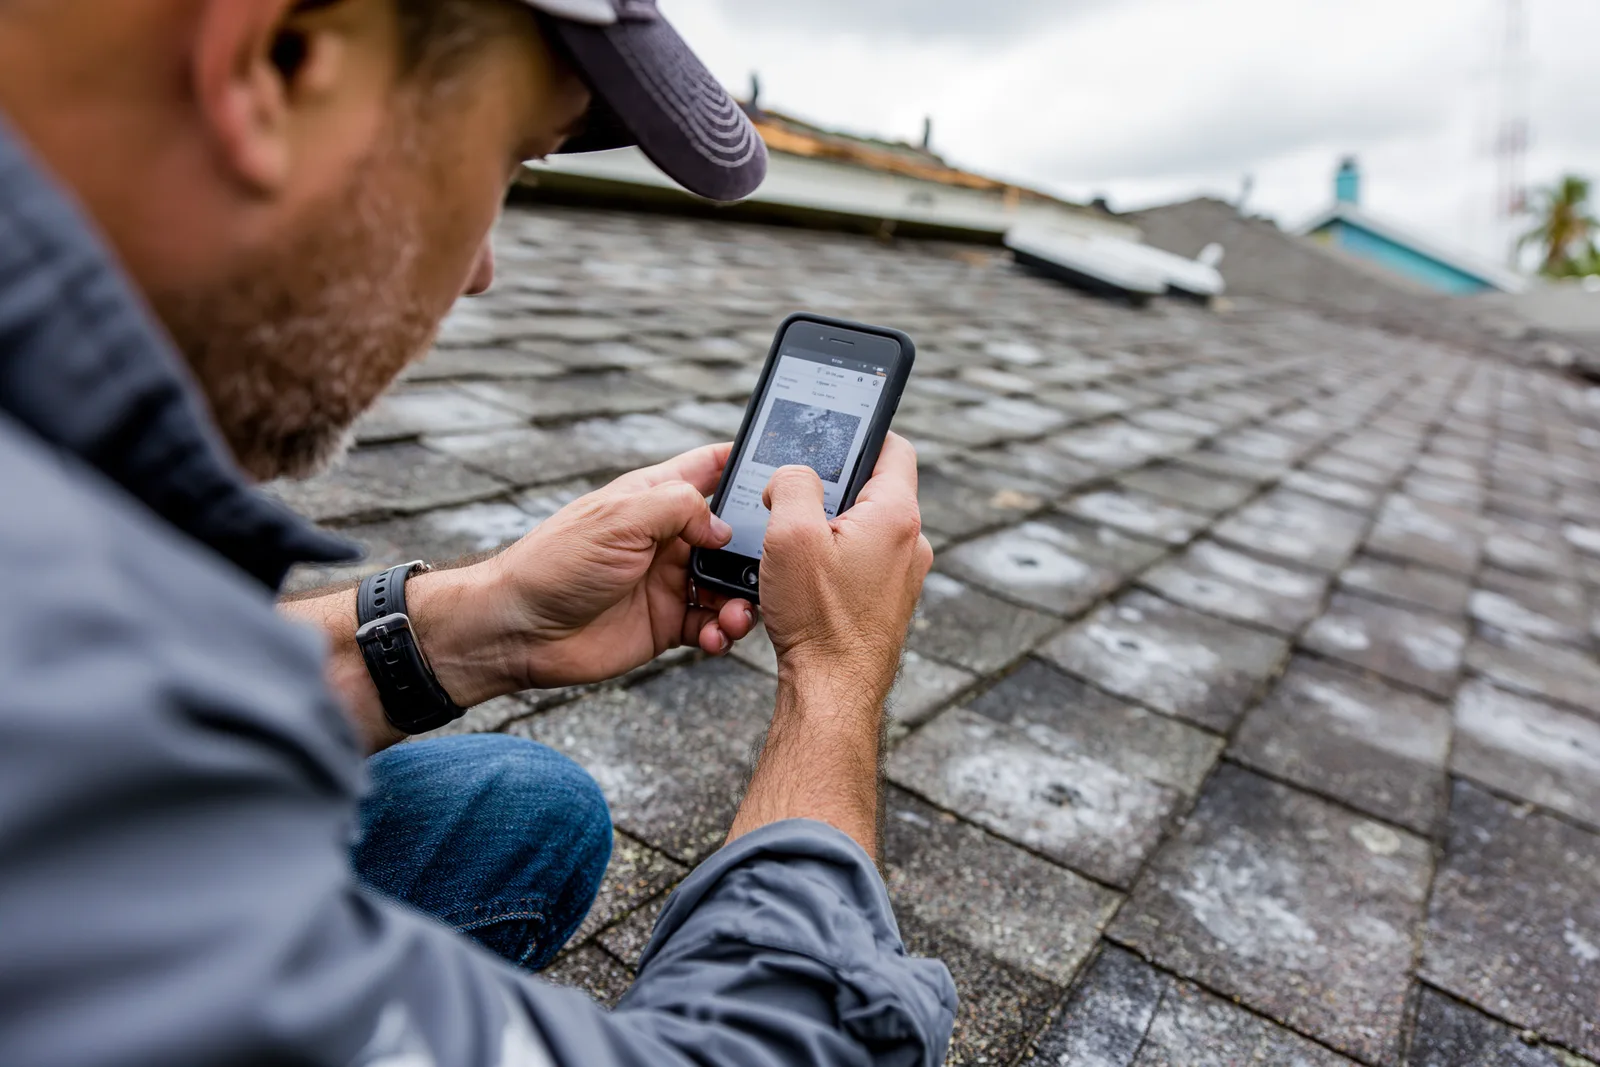
Temporary protection, damage assessment, the insurer’s inspection and construction planning have different jobs. Coverage and payment follow the policy.
Active water entry and safety come first. Suitable temporary protection can limit further exposure; keep the related records.
The roof condition and measured quantities define the repair or replacement scope. New concealed conditions can add construction work.
The adjuster and insurer assess the covered loss. Policy terms control the deductible, depreciation and payment requirements.
The Kansas Department of Insurance explains homeowner coverage and claims settlement.
Kansas home and renters guidance explains reporting, adjuster assessment and questions about coverage or settlement.
Construction findings and the roof scope support the work discussion. They do not guarantee claim approval or override the policy.
Explore storm damage roofing
Request a free inspection and discuss the physical roofing work alongside your insurance questions.